Florida Personal Property Bill of Sale Template (Free PDF)
A Florida personal property bill of sale becomes important when privately buying or selling untitled items such as furniture, electronics, tools, collectibles, appliances, hobby equipment, or household goods. In many real-world transactions, the document functions as the only written proof showing who sold the property, who purchased it, what was transferred, how much was paid, and whether the item was sold “AS IS.”
That documentation matters far more once the transaction involves higher-value property. Under Florida law, a contract for the sale of goods priced at $500 or more generally requires a sufficient record signed by the party against whom enforcement is sought to be enforceable, subject to exceptions under Fla. Stat. § 672.201. Private sellers often discover this problem only after a payment dispute, ownership challenge, chargeback allegation, or damaged-property claim appears weeks later.
This bill of sale is different from bills of sale used for titled property such as motor vehicles, boats, or mobile homes. Those transactions, however, carry separate Florida title-transfer laws, registration procedures, and statutory disclosure requirements that do not typically apply to ordinary untitled personal property.
Candice Hayden, Legal Writer
Carly Johansson, Florida Contract Attorney Last Updated: October 21, 2026
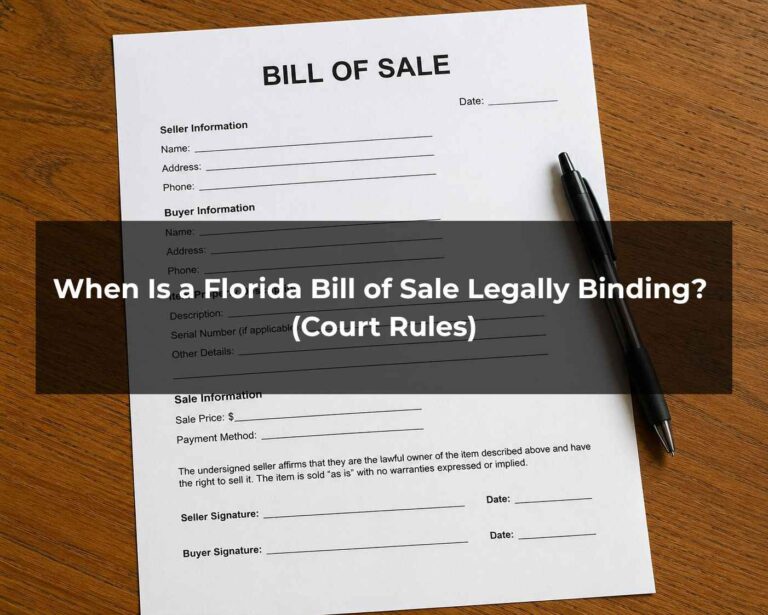
Florida Personal Property Bill of Sale Template
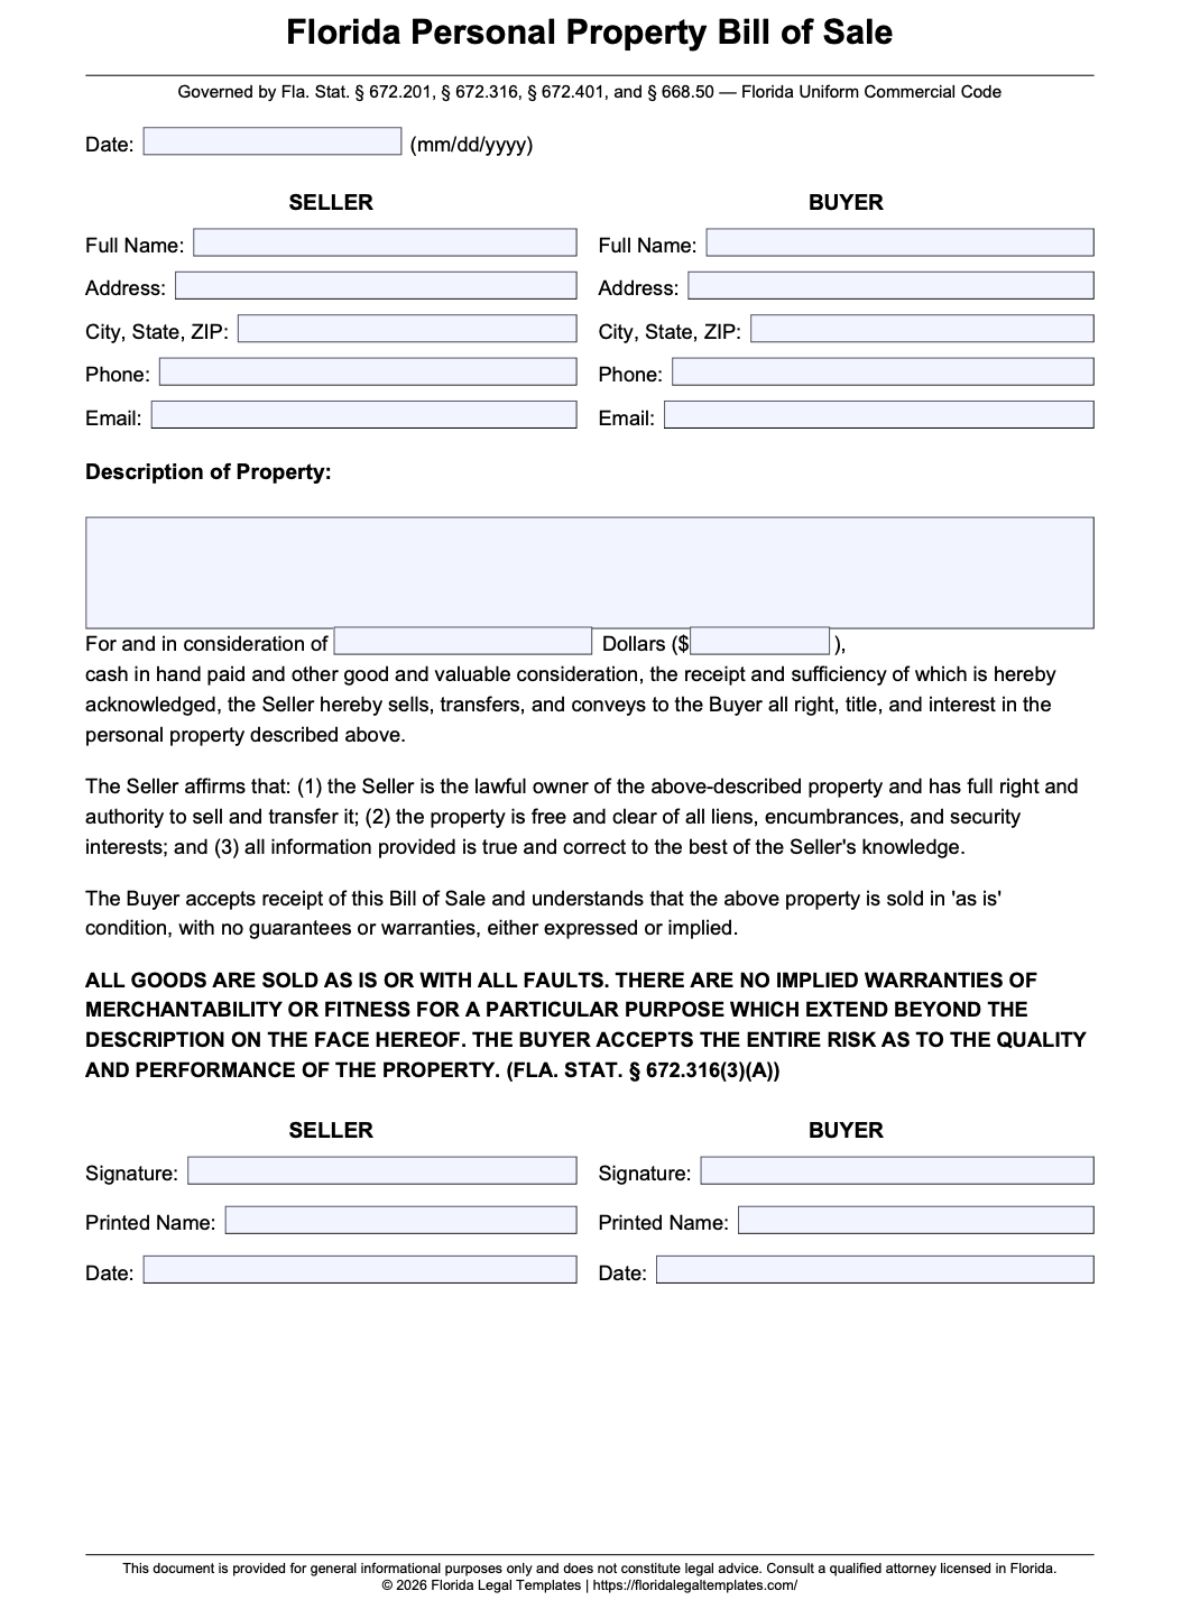
A Florida personal property bill of sale template is designed for private transfers of general tangible personal property between individuals. Additionally, most versions are available in printable and fillable PDF or Word formats, making them easier to complete and keep for future reference.
Common uses include:
- Garage sale transactions
- Facebook Marketplace sales
- Furniture transfers
- Electronics sales
- Appliance sales
- Collectible transactions
- Household goods transfers
- Tool and hobby equipment sales
Most forms contain:
- Buyer and seller information
- Property descriptions
- Purchase price terms
- Delivery details
- Condition disclosures
- Warranty disclaimers
- Signature sections
A standard template may not adequately protect the parties when the transaction involves:
- Seller financing
- Installment payments
- Commercial inventory sales
- Titled vehicles or vessels
- Secured collateral
- High-value disputed assets
- Business asset transfers
Those situations often require additional agreements and security-interest language or Florida UCC filings beyond a basic bill of sale.
What Makes a Florida Personal Property Bill of Sale Different From Other Bills of Sale?
This document exists primarily to prove the lawful transfer of untitled personal property in private transactions. Unlike a motor vehicle bill of sale or motor boat bill of sale, it is not normally tied to state title registration systems.
It also differs from:
- Commercial invoices used by retailers
- Business asset purchase agreements
- Firearm-specific transfer documents
- Consignment agreements
- Secured transaction paperwork
The legal focus here is narrower and more practical: documenting ownership transfer, payment terms, possession timing, and liability allocation between private parties.
Florida personal property sales are heavily influenced by Uniform Commercial Code sales law under Chapter 672. That creates issues many casual sellers overlook, especially involving:
- “AS IS” disclaimer language
- Oral agreement enforceability
- Risk-of-loss timing
- Warranty disputes
- Seller-financing problems
Most people using a Florida personal property bill of sale want a simple record of what changed hands, what the buyer paid, and what the parties agreed about the item’s condition. That record becomes especially useful when the transaction later turns into a dispute over payment, delivery, or ownership.
When a Florida Personal Property Bill of Sale Is Commonly Used
This form commonly appears in:
- Household property sales
- Craigslist or Marketplace transactions
-
Estate cleanouts and inherited property sales can create ownership disputes if authority to sell the property is unclear.
- Downsizing sales
- Antique and collectible transactions
- Electronics transfers
- Tool sales
- Cash transactions between strangers
- Family property transfers
Many sellers also use the document specifically to include conspicuous ““AS IS” bill of sale language intended to reduce future complaints about condition or functionality.
The document should not be relied upon alone when the transaction involves:
- Titled property
- Commercial merchant inventory
- Seller-financed collateral
- Consignment arrangements
- Suspected stolen property
- Cross-state secured transactions
Key Florida Laws That Affect a Personal Property Bill of Sale
Florida Statutes That Directly Affect Private Personal Property Sales
| Topic / Issue | Florida Legal Rule | Governing Statute |
|---|---|---|
| Statute of Frauds | Sales over $500 generally require a signed writing for enforcement | Fla. Stat. § 672.201(1) |
| Warranty Disclaimers | “AS IS” and merchantability disclaimers must be conspicuous | Fla. Stat. § 672.316 |
| Risk of Loss | Private-sale risk can transfer upon tender of delivery | Fla. Stat. § 672.509(3) |
| Legal Capacity | Florida generally removes the disability of nonage at age 18 under Fla. Stat. § 743.07, but separate rules and capacity issues may still affect whether a particular contract is enforceable. | Fla. Stat. § 743.07 |
| Seller Financing | Seller-financed transactions may require a security agreement and, unless an exception applies, a financing statement filed in the proper office to perfect the seller’s security interest under Fla. Stat. Chapter 679. | Fla. Stat. Chapter 679 |
| Contract Limitation Periods | For sales of goods governed by Florida’s UCC, an action for breach of contract generally must be brought within four years under Fla. Stat. § 672.725, whether the agreement is written or oral, subject to the statute’s provisions. | Fla. Stat. § 672.725(1) |
| Unconscionability | A court may refuse to enforce a contract or clause it finds unconscionable, or may limit its application, under Fla. Stat. § 672.302. | Fla. Stat. § 672.302 |
| Casual Sale Tax Rules | Isolated private sales may qualify for exemption treatment | Fla. Stat. § 212.02(2) |
Florida’s sales laws become highly relevant once disputes arise. Many informal cash sales begin with trust-based verbal agreements but later collapse when parties disagree about condition, payment status, pickup timing, or ownership.
For example, sellers often assume typing “sold as seen” into a receipt automatically eliminates liability. Under Florida law, ineffective or hidden disclaimers may fail entirely if they are not conspicuous or properly drafted. Courts frequently examine whether the buyer had clear notice of the disclaimer before the transaction closed.
Review the state’s baseline rules via Fla. Stat. § 672.201(1)(Statute of Frauds), the Fla. Stat. § 672.316(Warranties) and Fla. Stat. § 672.509(3)(Risk of Loss). When a seller-financed sale requires perfection by filing, the financing statement generally must be filed with the Florida Secured Transaction Registry under Fla. Stat. § 679.5011, unless a statutory exception or different filing rule applies.
How These Laws Affect Real Transactions
Oral agreements become particularly dangerous once property values exceed $500. A buyer may claim additional items were included. A seller may insist full payment was never received. Without written evidence, both parties face major evidentiary weaknesses.
Risk-of-loss rules also surprise many private sellers. Under Florida law, For a private sale by a nonmerchant, risk of loss generally passes to the buyer on tender of delivery under Fla. Stat. § 672.509(3), unless the parties agree otherwise or another UCC rule applies. Whether tender occurred depends on the delivery arrangements and the circumstances. That means an item damaged after tender of delivery—but before actual pickup—can become a contested issue.
Seller-financed transactions create another common problem. A simple bill of sale rarely provides sufficient protection if the buyer defaults after taking possession. Without properly structured security-interest documentation and possible UCC filings, repossession rights can become legally difficult.
Clauses That Carry Special Legal Importance
The most important provisions usually include:
- Property identification language
- Purchase price terms
- Delivery and pickup timing
- “AS IS” disclaimer wording
- Payment acknowledgment
- Signature authentication
- Installment-payment terms
- Security-interest clauses
Each provision answers a question that can become important later: what was sold, how much was paid, when delivery occurred, and what warranties were excluded. Leaving those details vague can make a later dispute much harder to resolve.
How to Properly Describe Personal Property in the Bill of Sale
Vague descriptions are one of the fastest ways to create ownership disputes.
Instead of writing:
“Used electronics”
A stronger description would identify:
- Brand
- Model number
- Serial number
- Quantity
- Cosmetic condition
- Included accessories
This becomes especially important for:
- Electronics
- Collectibles
- Tools
- Furniture
- Hobby equipment
- Bulk property sales
Photographs, receipts, and attached inventories can substantially strengthen evidentiary value. In estate cleanouts or moving sales, parties often later disagree about whether certain items were included. Detailed attachments reduce that risk.
Using “AS IS” Language Correctly in Florida
An “AS IS” clause is designed to limit implied warranties and shift quality-related risk toward the buyer.
Florida law also requires sellers to specifically use the word “merchantability” when they disclaim the implied warranty of merchantability.
An “AS IS” clause does not protect sellers who intentionally conceal defects or commit fraud. A seller who knowingly lies about flood damage, stolen components, counterfeit collectibles, or major functional problems may still face legal exposure despite disclaimer language.
How to Create and Sign a Florida Personal Property Bill of Sale
A practical drafting workflow usually follows this order:
- Identify the buyer and seller
- Describe the property in detail
- State the purchase price
- Clarify payment timing
- Address pickup or delivery terms
- Add warranty or “AS IS” language
- Confirm possession transfer
- Sign and exchange copies
Florida law does not generally require notarization for an ordinary bill of sale covering untitled personal property, although a separate law or document requirement may apply to a particular transaction.
Still, notarization may help in situations involving:
- Fraud allegations
- Estate disputes
- Ownership challenges
- Higher-value property
- Cross-state enforcement concerns
Cash transactions between strangers should also document the exact payment date and amount received.
Risk of Loss Problems Buyers and Sellers Often Overlook
Many disputes occur after payment but before pickup.
For example:
- A garage roof leaks onto stored furniture
- An appliance is damaged during loading
- Electronics are stolen after payment but before collection
Florida’s “tender of delivery” rules can significantly affect who absorbs the financial loss.
Clear drafting helps reduce uncertainty. Strong agreements usually specify:
- Exact pickup deadlines
- Storage responsibility
- Transportation responsibility
- Possession-transfer timing
- Risk allocation after payment
Without those details, a later dispute may turn on when Florida law treated delivery as tendered and whether the parties had agreed to a different risk-of-loss arrangement.
Seller Financing and Installment Payment Risks
A standard bill of sale is often inadequate for financed transactions.
Once installment payments enter the picture, disputes commonly arise involving:
- Missed payments
- Repossession rights
- Ownership timing
- Damage before payoff
- Priority creditor claims
Sellers sometimes assume they retain ownership until the final installment is paid. However, under Fla. Stat. § 672.401(1), a seller’s reservation of title in goods already delivered is generally limited to a security interest, so the transaction should be structured accordingly. Protecting a seller’s security interest against third parties generally requires compliance with Chapter 679, including attachment and, when required for perfection, filing a financing statement.
The distinction matters most when the buyer defaults or a third party later claims an interest in the property, because the seller’s rights then depend on the transaction’s Chapter 679 security-interest structure.
Payment Reversals Can Create Ownership Disputes Even With a Signed Bill of Sale
A signed bill of sale proves what the parties agreed to, but it does not guarantee that the seller has actually received irreversible payment. Many private sellers do not realise this until a payment problem arises, such as when a buyer pays by personal check, uses a fraudulent cashier’s check, or disputes or reverses an electronic payment.
If the agreement states that ownership transfers immediately upon signing or delivery, the buyer may argue they became the lawful owner even though the seller never received final payment. Unless the contract clearly conditions the transfer of ownership or possession on cleared funds, recovering the property may require a separate civil action instead of simply demanding its return. Florida’s UCC generally ties the passage of title to the seller’s completion of physical delivery, unless the parties explicitly agree otherwise. See Fla. Stat. § 672.401(2).
Also, For higher-value transactions, many experienced private sellers include language stating that possession and title transfer only after the seller receives collected funds, not merely after the buyer tenders payment. That sentence can reduce arguments over whether delivery occurred before payment became final, especially when buyers use checks, wire transfers, or peer-to-peer payment platforms. It also creates a much clearer record if litigation later turns on the sequence of payment, delivery, and ownership.
Common Mistakes That Cause Disputes in Florida Personal Property Sales
Before signing, check that the Florida bill of sale identifies the property, records the payment terms, and explains when delivery and possession occur. For a sale of goods priced at $500 or more, also consider the signed-record requirement under Fla. Stat. § 672.201.
A generic bill of sale can leave Florida-specific issues unstated, particularly the delivery terms, warranty disclaimer, and payment conditions that matter under Chapter 672.
Financial consequences may include:
- Lost property claims
- Failed lawsuits
- Payment disputes
- Ownership litigation
- Inability to prove terms
- Unenforceable disclaimers
Situations Where a Personal Property Bill of Sale May Not Fully Protect You
A Florida personal property bill of sale records the transfer; however, it cannot resolve every problem with the sale. For example, a signed form does not establish that the seller owns stolen property, nor does it replace the security-interest requirements that may apply to financed goods under Chapter 679. Therefore, if someone disputes ownership or separate title laws apply to the property, resolve those issues before relying on a general bill of sale.
Florida courts also retain authority under unconscionability principles to refuse enforcement of extremely unfair provisions.
Related Florida Documents Often Confused With This Form
Several related documents serve very different legal purposes:
- Vehicle bill of sale
- Boat bill of sale
- Firearm bill of sale
- Asset purchase agreement
- Security agreement
- Sales receipt
- Consignment agreement
A security agreement, for example, focuses on collateral rights after default. A vehicle bill of sale connects to title-transfer procedures. A sales receipt may only acknowledge payment without allocating legal risk.
These documents can look similar because they all relate to property, but the legal function changes once the transaction involves title registration, collateral, inventory, or continuing obligations.
Frequently Asked Questions
Is a written personal property bill of sale required in Florida for items over $500?
Under Florida’s UCC statute of frauds, sales of goods priced at $500 or more generally require a signed writing to be enforceable against the party being sued. Fla. Stat. § 672.201(1)
Does an “AS IS” clause fully protect a Florida seller from future claims?
No. Fraud, intentional concealment, or ineffective disclaimer drafting can still create liability exposure.
Can a Florida personal property bill of sale be challenged in court?
Yes. However, courts may also examine issues such as legal capacity, forged signatures, unconscionability, unclear drafting, or fraudulent conduct when determining whether a bill of sale is enforceable.
Should a Florida personal property bill of sale be notarized?
Notarization is not generally required for validity, but it may strengthen evidentiary value in disputed transactions.
What happens if the property is damaged before the buyer picks it up?
That depends heavily on the delivery terms and Florida risk-of-loss rules under Fla. Stat. § 672.509(3).
Can this document be used for installment payments or seller financing?
It can document the sale, but financed transactions often require additional secured-transaction documents and possible UCC filings.
Final Review Checklist Before Signing
Before signing a Florida personal property bill of sale:
- Verify property descriptions
- Confirm payment terms
- Review “AS IS” wording
- Ensure signatures are complete
- Clarify possession-transfer timing
- Keep copies for both parties
- Attach supporting documents or photos
- Confirm the property is untitled and not separately regulated
Careful drafting at the beginning of the transaction is usually far less expensive than trying to reconstruct the agreement after a dispute develops.
Legal Disclaimer: This Florida personal property bill of sale article provides general legal information for educational purposes only and is not legal advice. However, Florida law can vary depending on the property, transaction terms, and specific circumstances. For high-value, financed, disputed, or regulated property, consider consulting a Florida attorney before signing.